A fund can buy Bitcoin long before settling who will safeguard it. Someone must authorize transfers, check balances, and respond when a service provider fails. Those tasks rarely make headlines alongside Bitcoin purchases and exchange-traded fund launches. However, they determine whether a firm can offer direct crypto exposure.
The Securities and Exchange Commission returned to this problem on October 1, 2026. Its proposal covers registered investment advisers and regulated funds. If adopted, the changes could widen access to crypto assets while preserving firms’ responsibilities to safeguard client holdings.
A Custody Provider Must Meet More Than Technical Needs
Existing rules generally require advisers to keep client funds and securities with qualified custodians. Banks and certain broker-dealers have handled that responsibility for years. The arrangement separates the people choosing investments from the businesses safeguarding them. It also produces records for auditors and clients.
Crypto introduces a problem those familiar arrangements do not always solve. A custodian might support Bitcoin but decline to hold a newer token. Another provider might understand the network but fail to qualify under federal securities rules. That leaves an adviser with an investment choice and no suitable place to keep the asset.
The SEC proposes a narrow exception. Under the proposal, an adviser could hold certain client crypto assets directly after determining that no qualified custodian is available. The adviser would need to document its findings and review the market for available custodians every quarter. Once a qualified provider became available, the adviser would need to transfer the assets as soon as reasonably practicable.
This approach would not make self-custody the default for every crypto investment. Instead, it would tie that option to a specific custody gap. Firms using the proposed exception would also take on responsibilities that outside custodians often perform.
Private Keys Turn Routine Transfers Into Control Decisions
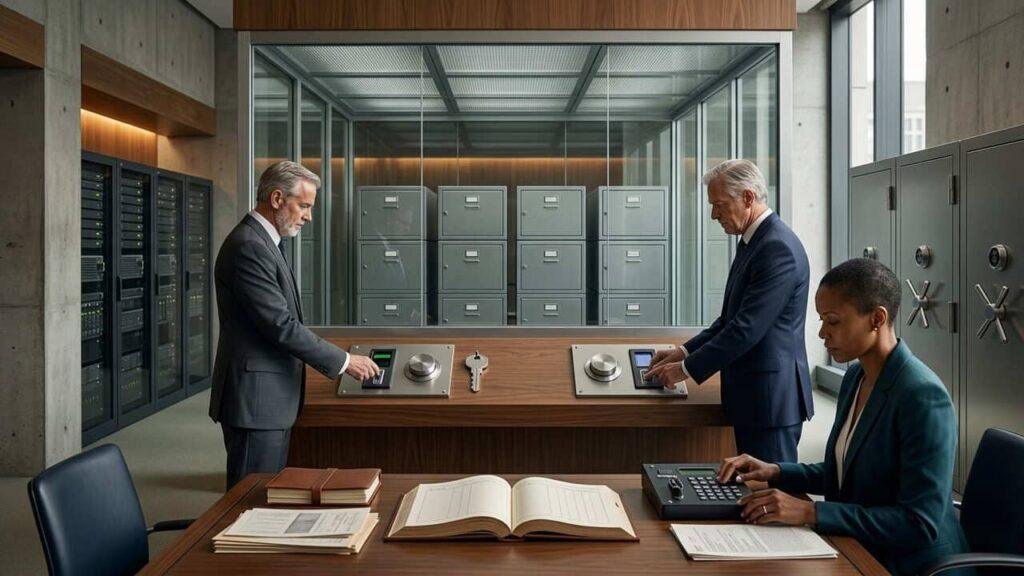
In crypto, access to private keys can mean access to the assets themselves. For an investment firm, that makes a simple transfer an issue of internal authority. The proposed safeguards would require joint transaction approval by at least two people. Advisers would also have to keep each client’s self-custodied assets at separate blockchain addresses.
Those addresses matter because a public blockchain records transactions without automatically identifying the customer behind each wallet. Separate addresses could make client holdings easier to distinguish. Account statements would identify the relevant network, balances, and transfers. Clients could then compare those records against information visible on the blockchain.
The proposal also calls for cybersecurity controls, independent internal control reports, and periodic reviews. These checks would cover key access, operating safeguards, and the accuracy of client records.
There is a legal side, too. The SEC proposes written agreements addressing the treatment of self-custodied assets under applicable state law. Such contracts would help define client interests and the adviser’s role. Fund boards would also have additional oversight duties when a regulated fund used adviser self-custody under the proposed framework.
The Next Test Happens Away From Trading Screens
The proposed changes would also offer a path for certain state trust companies to custody crypto assets. Advisers and funds would need to assess the firms’ supervision, financial position, and controls. These reviews would continue after the initial appointment. Client assets would need to remain separate from the custodian’s own holdings under the proposed requirements.
For institutions, custody decisions run through several departments. Investment teams consider the asset, lawyers examine ownership rights, and operations staff assess recordkeeping. Auditors need a clear account of balances and activity. No single approval from a trading desk resolves those questions.
Spot Bitcoin exchange-traded products illustrate the difference. In January 2024, the SEC approved the listing and trading of spot Bitcoin exchange-traded products, giving investors another way to obtain Bitcoin price exposure through securities accounts. Holding ETF shares, however, differs from directly controlling tokens across multiple networks. A broader crypto strategy creates custody decisions that an ETF purchase does not.
The SEC’s proposal remains open for public comment until December 7, 2026. Its adviser provisions cover crypto funds and securities, while fund provisions address crypto securities and similar investments. For now, firms must continue following existing rules. Institutional crypto adoption depends partly on whether future custody arrangements can fit those everyday obligations.